 Here’s our latest interview with a millionaire as we seek to learn from those who have grown their wealth to high heights.
If you’d like to be considered for an interview, drop me a note and we can chat about specifics.
This interview took place in April.
My questions are in bold italics and their responses follow in black.
Let’s get started…
OVERVIEW
How old are you (and spouse if applicable, plus how long you’ve been married)?
I am 48 and my spouse is 49.
We’ve been married for 15 years.
Do you have kids/family (if so, how old are they)?
We have no children.
What area of the country do you live in (and urban or rural)?
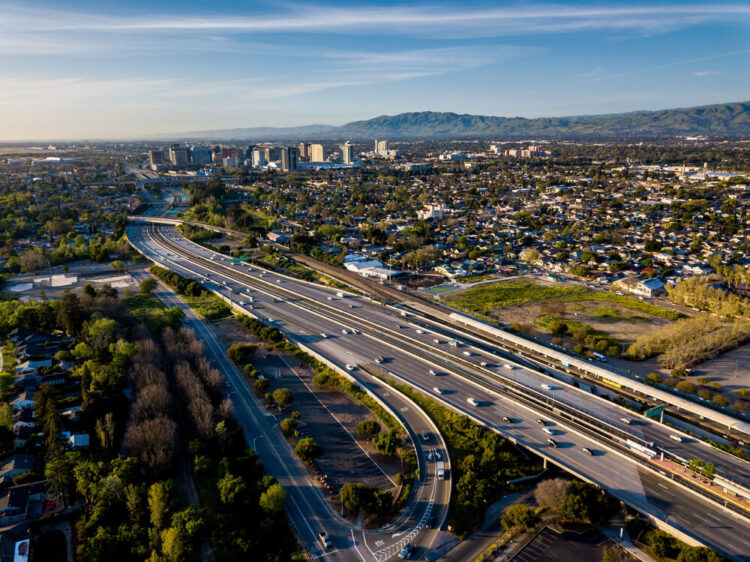
We live in an urban area, in the middle of Silicon Valley.
What is your current net worth?
Our current net worth is approximately $2.4 million.
What are the main assets that make up your net worth (stocks, real estate, business, home, retirement accounts, etc.) and any debt that offsets part of these?
In our retirement accounts, we have approximately $1.2m, which are mostly in Roth accounts.
In our taxable non-retirement accounts, we have approximately $700k. We also have approximately $500k equity in our home.
EARN
What is your job?
I would consider myself semi-retired. I do still consult with a couple of companies on a minimal/limited basis, providing strategic and operational expertise.
Before this, I was primarily in IT/software and advanced to executive level leading multiple teams in AI/data/analytics for a multinational conglomerate.
My wife is a full-time engineer at an aerospace company.
What is your annual income?
Last year I earned approximately $100k from the minimal consulting work I do.
My wife earned $145k from her job.
Tell us about your income performance over time. What was the starting salary of your first job, how did it grow from there (and what you did to make it grow), and where are you now?
My income performance has been neither standard nor smooth. I’ve also kept less than meticulous records, so these numbers are from memory.
In the 1990s, while in high school, I got paid $25/hr ($50k/yr equivalent) for tutoring other kids. That became $4.75/hr ($9,500/yr equivalent) in college for the work-study job that was part of my financial aid package.
In the early 2000s, grad school paid $1500/mo ($18k/yr equivalent) for being a teaching assistant or research assistant, while my summer internships at tech companies paid $37.50/hr ($75k/yr equivalent). My first full time job after leaving grad school in 2006 paid $92k/yr.
Unfortunately, the housing crisis exerted significant financial pressure, and four years later, it was only ~$98k/yr.
In 2010, I left for a startup and was paid minimally. In 2014 I came to accept that the startup was going nowhere, and applied for jobs everywhere.
At this point, the economy was doing better, and I leveraged everything I learned from the startup and landed a role at $150k/yr base. In 2016 I took an offer at another company for $185k/yr base.
The next year I went to another company for $205k/yr base. In 2019, I changed companies again, this time at $220k/yr base. 5 years later I left this company having reached $260k/yr base.
Prior to the 2 of us meeting, my wife was an executive admin for a small company that paid very little. Once we married, she expressed a desire to go back to school for an engineering degree, and surprisingly to me, in aerospace engineering.
After a few years, she graduated with both bachelor’s and master’s degrees. It was in the middle of the pandemic, and she was fortunate to land an entry-level engineering role at her current company.
The starting salary was $126k/yr, and over 4 years and a promotion, is now $145k/yr.
What tips do you have for others who want to grow their career-related income?
Short answer: Show management how you contribute directly to the company’s bottom line.
Longer answer: At a high level, one can think of a role as having 3 potential components: 1) ensure ongoing operations/maintenance, 2) generate efficiencies, and 3) generate revenue/growth. Roles in cost center departments (those that are primarily #1) are generally constrained, as a company will do as much as possible to limit its cost increases.
For cost center roles, the key is to maximize one’s contributions that are tied directly to #2 or #3. An example would be the financial analyst who identifies a way to save the company 1% on corporate taxes, or the engineer who implements a feature that closes a key account.
Roles in revenue centers (those are primarily #3) will grow their income as the revenues (i.e. sales) grow, so the approach here would be to work on a product/service in a growing market.
What’s your work-life balance look like?
In my last full time corporate role, I would say that I had a pretty good work-life balance, for primarily 2 reasons. First, I got to a level where my contribution was no longer tied to the time that I put in.
My value became about being able to articulate a strategic vision, the challenges to overcome, the approach to solving those challenges, and the rationale for each of these.
These days I spend a couple hours a week working with clients, and the rest of the time I do a lot of reading and researching (of whatever topic tickles my fancy) while also playing house-husband and handyman.
My wife’s job generally has a pretty good work-life balance and returns home at the same time each day and is able to leave work at work. There are a couple times a year when they are doing a launch and thus she has to shift her hours.
Do you have any sources of income besides your career? If so, can you list them, give us a feel for how much you earn with each, and offer some insight into how you developed them?
At this point in time, passive income via interest and dividends have become non-trivial. Last year, this approached $20k in taxable accounts.
We also rent out our extra bedroom during the summer months to one student interning at a local tech company. I remember when I was in grad school and had to find housing in the area for my tech company internship, and the challenges of renting a place via Craigslist.
It’s quite a bit easier now with AirBnB, though they take a significant cut. Nevertheless, this nets us close to $10k for the ~3 months. For summer 2026, there looks to be a 25-35% jump in comparables over 2025.
Currently, we do not earn income from other side gigs or assets.
SAVE
What is your annual spending?
Our core spending is $72k/yr. There’s also income tax, which is variable.
Beyond that, our discretionary spending is primarily spent on travel.
What are the main categories (expenses) this spending breaks into?
Main categories for core spending include housing (mortgage, property tax, insurance), utilities (water, gas, electric, internet, phone), cars, and food (groceries and dining out).
Do you have a budget? If so, how do you implement it?
We do not have a budget in the sense where we use it to determine discretionary spending. Our discretionary spending is primarily in travel, and we are fortunate to do so without worry.
Even though we don’t explicitly budget our travels either, it typically comes out to around $1000-$1500 per RT flight, and $1000-$1500 per week for housing and food.
What percentage of your gross income do you save and how has that changed over time?
Since our spending has stayed pretty consistent over time, the primary driver of the change in the savings rate is our income. In 2025, I estimate that we saved $120k of $250k gross income which comes out to 48%.
If I go back a couple years, in 2023 I estimate we saved about $300k of $440k gross income, which would result in a 68% savings rate.
What’s your best tip for saving (accumulating) money?
The amount of money saved is a function of the amount of money earned and the amount spent.
My answer to this question would be to refer the reader to the previous question regarding growing career-related income, and the next question which addresses spending less money.
What’s your best tip for spending less money?
We are strong believers in 2 complementary philosophies, and I’ll touch on both here:
- BIFL (buy it for life). We tend to buy quality products that we expect to last for a long time, and take care of them to ensure that. A corollary of BIFL for many things is that secondhand is as good as (if not better than) new.
- DIY (do it yourself). We live in a convenience oriented world where it’s possible to pay someone for the product or service. While doing so buys time, it’s only a good trade if the time can be applied towards something valuable, and not more screen time doom-scrolling.
Our car ownership exemplifies our BIFL philosophy. We have 2 cars– one is 13 years old (hers), the other is 24 (mine).
Our motivation for keeping such well aged cars is not primarily to save money (though it certainly helps!), but rather, they are more than sufficient for our needs. The details:
In 2002, I purchased my car new, and over time I feel more confident that I could have purchased a secondhand one instead and it would have served me just as well. After all, the car still runs perfectly, with the most recent issue being four years ago when it was running rough, fixed by replacing a clogged check valve.
Regarding our other car, my wife needed a replacement car in 2016, as hers was on its last legs (the head gasket was leaking coolant into the engine which created massive sludge issues). We bought a CPO (certified pre-owned) of a reliable model/make car that was 3 years old with 31,000 on the odometer for $19,500 that would have cost >$32,000 new.
At the time I was amazed that we got the car for less than what mine had cost when new 12 years earlier. This has been her daily driver over the last 10 years, and during that time, our primary spending on the car has been insurance, maintenance (e.g. regular oil changes), and gas.
The CPO warranty covered any initial issues (very minimal), so our only repair costs on this car have been replacing the windshield (when it was cracked by a rock on the highway), and a set of new tires (also by road debris on the highway).
The consequence of the BIFL mentality is that we see very little utility from getting newer ones. At one point during the pandemic, we briefly flirted with getting an EV potentially to replace my car.
Ultimately, the hassle of electric charging and additional costs of a new car, even with all the incentives, deterred us from pulling the trigger.
With respect to DIY- what started as interesting things to do during the pandemic (e.g. baking bread) has led to learning about different forms of fermentation and the resulting products. From this perspective, the most valuable things we get from DIY is knowledge and self improvement, as well as healthier food, with money savings being a side benefit.
What is your favorite thing to spend money on/your secret splurge?
We enjoy traveling and seeing more of the world.
People, places, food, cultures are so diverse and beautiful, and all of that is best appreciated in person and in-situ.
INVEST
What is your investment philosophy/plan?
Unless one has both knowledge and understanding of the markets and the industry, passive investing via index ETFs is the best approach.
What has been your best investment?
This has been our marriage, for at least 2 reasons.
First, having someone who has the same lifestyle and financial philosophy means having a partner to overcome challenges together, and that makes all the difference.
Second, for me personally, having invested in her career change, it’s great to see her happy at a job that also now funds our cash flow.
What has been your worst investment?
Financially, I would say it would be either the startup I did in 2010 (as I burned through all my savings) or the stock options from a couple of other companies, which I exercised but never cashed out before they went bankrupt.
What’s been your overall return?
To be candid, we have not tracked this.
I would say it would be pretty close to the overall market given our passive investment strategy.
How often do you monitor/review your portfolio?
We generally review and make adjustments to our portfolio 3-4 times a year. The adjustments are primarily to return the portfolio to more closely reflect the original allocations.
We have also dipped our toes into a robo-investor account, which automatically readjusts the portfolio and also performs tax loss harvesting. Eventually, it would be nice to have everything automated, so that’s an item on the to-do list.
NET WORTH
How did you accumulate your net worth?
We have accumulated our net worth initially with a combination of earning and saving.
As the savings have grown, growth from (passive) investing is starting to take over.
What would you say is your greatest strength in the ESI wealth-building model (Earn, Save or Invest) and why would you say it’s tops?
Our greatest strength would be Saving. An example of this is the purchase of our home.
Starting at the end of 2014 with practically zero savings (due to startup failure), we were able to save >50% of the sole income we had at the time (mine) over the next 3.5 years, enabling us to put 20% down on a median priced home in the middle of Silicon Valley in 2018.
What road bumps did you face along the way to becoming a millionaire and how did you handle them?
The greatest road bump was probably getting to practically zero net worth as a result of doing a startup.
One could say I was young and foolish, but I always had the confidence that I could find a job if that failed so it would be only a temporary setback.
What are you currently doing to maintain/grow your net worth?
Our net worth continues to grow, albeit at a much slower rate since I’ve stepped back from full time employment.
My wife is still working at her full time job, and that provides the cash flow and additional savings to grow our net worth.
Do you have a target net worth you are trying to attain?
No specific target net worth. Using the 4% rule, we are able to cover our living expenses.
We also expect that our expenses will drop in retirement, as the rental income from our home will more than offset the mortgage (locked into historically low interest rate).
Since we know that we are already set for retirement, the question becomes what we want to be doing. For now, my wife is happy at her job and wants to continue working for the foreseeable future.
For me, I’m starting to plan for a retirement where the 2 of us can travel multiple times a year.
How old were you when you made your first million and have you had any significant behavior shifts since then?
I think we hit $1m net worth sometime in the middle of the pandemic. It’s difficult to say when exactly it was, as quite a few things happened around that time to help accelerate our net worth. These include
- Paying off my student loans from college and grad school
- In the middle of a 60 day period of an indirect rollover when the market crashed in March 2020, thus enabling investing proceeds at an immense discount, followed by a tremendous bull market
- Refinanced at historically low interest rate, thereby locking in a very low monthly mortgage payment. This alone saves us >$1000 a month, and an estimated $200k if we keep the house for the entire loan term.
- My wife finished school and started her job
What personal habits and/or traits have you developed that have made you successful at growing your net worth?
As discussed above, our BIFL and DIY mentality have been crucial in growing our savings. We also have high (relative to the rest of the country) incomes, which allow us to save more.
Finally, putting those savings into index funds means we have the US economic engine working for us.
What money mistakes have you made along the way that others can learn rom?
Hindsight is 20/20, so there are many “I wish I had invested in X back when…”. However, we can’t complain about where we are now.
As a result, I would say that I haven’t made too many mistakes when it comes to money. Others have pointed out that we could perhaps be less conservative with our financial decisions.
What advice do you have for ESI Money readers on how to become wealthy?
From my perspective, becoming wealthy is more easily accomplished with the right mindset. Growing earnings is more about growing one’s skillset and increasing one’s value to the customer.
Growing savings is easy; what’s hard for most people is not spending, and that requires one to think about the tradeoffs of that particular purchase. Growing investments requires very little action and a tremendous amount of patience.
FUTURE
What are your plans for the future regarding lifestyle?
At this point, I feel as if I’ve retired.
My wife is still working, so I feel as if I am in limbo, waiting for her to retire as well.
What are your retirement plans?
The only plans we have once retirement hits for both of us would be to do more traveling. The travel we envision, though, is a very slow travel.
Ideally, we would go and live somewhere for a few months to a year and integrate ourselves into the community there. We do have to keep in mind considerations around visa length and tax implications beyond a certain length of stay.
Are there any issues in retirement that concern you? If so, how are you planning to address them?
I think for most people a top concern in retirement is healthcare cost and access. For now we are both quite healthy and free of the many common health issues that affect friends our age. 🤞
There are 2 things we are doing to address/mitigate our future healthcare needs.
First, we have increasingly focused on being healthy. With respect to diet, in conjunction with our DIY nature, that includes cooking more, dining out less, consuming more healthy foods (e.g. leafy greens) and eliminating/reducing unhealthy items (e.g. sugar).
I recently learned that the USDA guideline for sugar intake is 50g/day. Given that we typically consume no sugar beyond the daily carb (rice, pasta, bread), I am optimistic that habits like this will help us stay healthy long term.
Second, traveling has exposed us to the availability of cost-effective medical services around the world, and that is something we expect to leverage, particularly given the amount of travel we intend.
MISCELLANEOUS
How did you learn about finances and at what age did it “click”?
In 1985, my parents opened a savings account for me and deposited $100 into the account.
At the time, the interest rate was 13%, and so it amazed me that every month the account got paid over $1 for doing nothing!
Who inspired you to excel in life? Who are your heroes?
I have great admiration for individuals who defy conventional wisdom and improve the human race. Examples would be the idea of heliocentrism (most famously Copernicus and Galileo) and the smallpox vaccine via cowpox infection (Edward Jenner).
In social/political conflicts- Dalai Lama, Nelson Mandela, Martin Luther King Jr. Mohammad Yunus with the idea of microlending.
Do you have any favorite money books you like/recommend? If so, can you share with us your top three and why you like them?
One that comes to mind is Benjamin Graham’s Intelligent Investor, which even Warren Buffett (who was Graham’s student) praises as one of the best books on value investing, for those who truly want to learn how to value companies. That said, the book is incredibly dense, but perhaps that’s why investors like Warren Buffett are so successful and so rare.
Here I am reminded of a conversation with Buffett that Jeff Bezos shared. While Buffett has been very successful, very few people copy what he does, because his is a “get rich slowly” scheme.
Another book is Mohammad Yunus’ Banker to the Poor. It’s such a simple idea that has such potential to lift groups of people (and particularly groups of women) out of poverty.
Do you give to charity? Why or why not? If you do, what percent of time/money do you give?
For a long time I participated in the microlending platform Kiva. As I observed that loans over time transitioned from entrepreneurial loans to personal loans, I reduced my participation there.
Additionally, the platform experience seems to have deteriorated over time.
At the moment we do not give money to charity. We are still looking for an organization with the strategic vision and fiscal discipline that aligns with our values.
Do you plan to leave an inheritance for your heirs (how do you plan to distribute your wealth at your death)? What are your reasons behind this plan?
As we do not have children, we have no obvious “heirs”.
Ideally, we would die with zero. However, that will unlikely be the case, and we have yet to decide what to do about that.

Leave a Reply